
Industry Insurance in Darwin
Contact Our Team
- Industry activities considered before cover
- Trades, construction, transport & rural sectors
- Australia-wide commercial insurance support
Insurance Shaped Around The Work You Do
At Blackadder Insurance Brokers, we look at how your business operates before discussing cover. From our base near Darwin, we work with trades, construction, transport, professional, rural and small business operators, helping clients Australia-wide understand the exposures their activities can create.
Our approach to industry insurance starts with the details: the work performed, where it happens, the people involved and any contractual requirements. We then approach insurers we deal with and explain the terms available, subject to each policy's limits, conditions and exclusions.
To talk through the insurance considerations for your industry, call our team on (08) 8981 4824.
Trades & Contractors
Trades and contractors can face risks involving tools, vehicles, worksites, customers and contractual obligations. We start by understanding the work performed, where it takes place and whether employees or subcontractors are involved. The insurance discussion may include public liability, commercial motor, plant and equipment, property or contract works, depending on the activities described. Our team can also review insurance limits or conditions required by principals and contracts. Because one trade can operate very differently from another, accurate descriptions of services and any changes in work are important when insurers assess the risk.
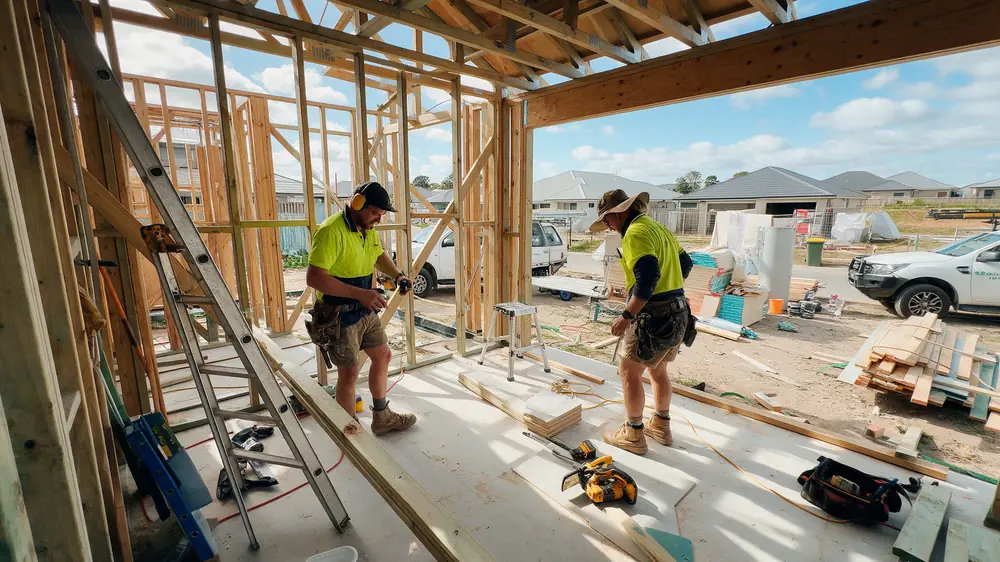
Construction
Construction businesses can have changing worksites, project values, subcontractor arrangements and contractual insurance requirements. We discuss the type of construction work undertaken, project size, equipment, vehicles, employees and the responsibilities assumed under contracts. Depending on the operation, relevant insurance categories may include contract works, liability, commercial motor, plant and equipment and other business cover. Our team can approach insurers we deal with and explain the terms available for the activities described. New project types, larger contract values or changes in operations should be raised because they can alter the information on which cover was arranged.
Transport
Transport operators can face insurance considerations involving vehicles, drivers, cargo-related exposures, depots and the distances or regions in which they operate. We look at the fleet, vehicle types, business activities, driver arrangements and claims history before discussing available insurance options. Depending on the operation, commercial motor, fleet, liability, property and other specialist transport-related cover may need consideration. Our team explains the terms offered by the insurers we deal with, including relevant excesses, conditions and exclusions. Changes to routes, vehicles, freight types or business activities can affect underwriting and should be disclosed when they occur.
Professional Services
Professional service businesses often rely on advice, expertise or deliverables rather than physical products, which can create a different set of exposures. We discuss the services provided, client types, contracts, staff, revenue and how information or technology is used in the business. Professional indemnity, cyber, management liability, property and other commercial covers may be relevant depending on the circumstances. Our team can help compare available options and explain how limits, excesses, exclusions and policy definitions differ. Clear descriptions of professional activities are important because insurers assess cover based on the services the business actually provides.

Rural & Agriculture
Rural and agricultural businesses can combine property, machinery, vehicles, livestock, liability and commercial activities across large areas of land. We take time to understand how the property is used, what is produced or operated there and which assets are central to the business. The insurance discussion may involve farm property, plant and equipment, commercial motor, liability and other cover relevant to the operation. Our team can approach insurers familiar with the risk and explain available terms. Changes in land use, machinery, activities or property values should be raised so the insurance information remains current.

Small Business
Small businesses are diverse, so insurance should reflect the activities and assets of the individual operation rather than a generic business label. We discuss what the business does, where it operates, its staff, property, equipment, vehicles, customers and contractual obligations. Depending on those details, relevant cover may include liability, property, business interruption, cyber, commercial motor or management liability. Our team can help organise the information insurers require and explain the available options in straightforward language. As a business grows or changes its services, premises or assets, its insurance arrangements may also need to be reviewed.
FAQs
Discuss Your Industry Risks